 Written by
County court – enforcement – practical guidance
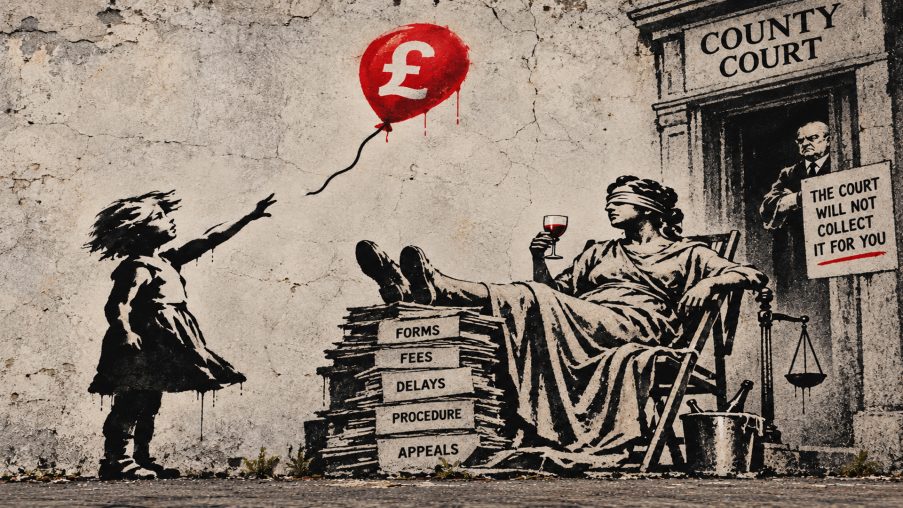
A county court judgment is a decision that money is owed to you, not a promise that it will arrive. The court will not collect it for you. This guide sets out the four main enforcement routes, what each costs in court fees, and how to match the route to what you actually know about the debtor.
Snapshot
Enforcement is a second piece of litigation that the winner has to start, choose and pay for. Each route targets a different part of the debtor’s finances: goods, wages, savings or property. Every application fee is spent at your risk even though it is added to the debt, so knowing the debtor’s circumstances before you apply is worth more than any single form.
Winning is not collecting
Many litigants in person assume that once judgment is entered, the machinery of the court will deliver the money. It will not. The court will not enforce the judgment unless you ask it to, and it is for you to choose which method of enforcement to use. Court staff can explain procedure, but the official guidance is explicit that they cannot tell you which method to pick. The judgment gives you rights; it does not exercise them for you.
That shift in responsibility carries a financial risk. Every enforcement step carries a court fee. The fee is added to what the debtor owes you, but if the enforcement fails, or the court refuses the application, the fee you have paid is not returned. Enforcement is therefore a series of small gambles, each sensible only if you have reason to believe the debtor has the asset the method targets. Where you are owed £5,000 or more, a bankruptcy petition is a further possibility, though the official guidance describes it as expensive.
Key distinction. A judgment establishes that the money is owed. Enforcement is how you turn that finding into payment. They are separate processes, and the second one is yours to drive.
Before you spend: find out what the debtor has
Each method is aimed at a different part of the debtor’s finances: goods point to a warrant of control, wages to an attachment of earnings order, savings to a third-party debt order, property to a charging order. Choosing blind is how fees are wasted. If the debtor is unemployed or self-employed, an attachment of earnings application is money spent on a route that cannot work.
If you know little about the debtor’s finances, there is a fact-finding step short of enforcement. An order to obtain information under Part 71 of the Civil Procedure Rules requires the debtor to attend court and answer questions on oath about their means; it is not itself a method of enforcement, but a way of discovering income, assets and spending so you can choose a method that fits. The application fee is £69, with a further fee if you want a bailiff to serve the order personally.
You can also search the Register of Judgments, Orders and Fines, which keeps details of county court judgments for six years, to see whether the debtor already has other unpaid judgments. And if your own financial situation makes the fees difficult, help with fees is available through form EX160A, but a separate application is needed for each fee.
Warrant of control: goods
A warrant of control authorises enforcement agents, still widely called bailiffs, to attend the debtor’s home or business, collect the money owed, or take goods to be sold at auction. Under the Tribunals, Courts and Enforcement Act 2007 the taking and selling of goods follows the statutory “taking control of goods” procedure in Schedule 12 to that Act, and only authorised enforcement agents may carry it out. The court fee to issue the warrant is £96.
The limits are practical as much as legal. You cannot ask the county court to issue a warrant where the amount to be collected exceeds £5,000, unless the judgment enforces a regulated agreement under the Consumer Credit Act 1974, which can only be enforced in the county court. Above that level the route is a transfer to the High Court for a writ of control, for which the sealing fee is £82 and the process is different and more complicated.
Even within the limits, a warrant is only as good as the debtor’s possessions. Enforcement agents cannot remove essential household items, a tradesman’s tools, or goods held under hire-purchase or rental agreements, and goods sold at auction often raise only a fraction of their original value. If the debtor rents a furnished room and owns little, the warrant is a £96 answer to a question you could have asked for free.
Attachment of earnings: wages
An attachment of earnings order is sent to the debtor’s employer and directs the employer to deduct a set amount from the debtor’s pay each pay day and send it to the court, which passes it on to you. The debtor must be employed: an order cannot be made against someone who is unemployed or self-employed, and where the creditor applies the court must be satisfied that the debtor has failed to make one or more payments required by the judgment. The fee is £139 for each debtor against whom an order is requested.
This is the slow, steady route: it converts the judgment into a standing deduction and works best where the debtor has a stable job. Its weakness is the mirror image of its strength. The court may not make an order, or may make one for only small instalments, where the debtor’s living expenses are greater than their earnings. A debtor on a modest wage may repay at a pace that tests your patience but eventually pays in full.
Third-party debt order: savings
A third-party debt order freezes money owed to the debtor by someone else, most often a bank or building society account, so that it can be paid to you instead. The application is made on form N349 and proceeds in two stages: an interim order made without a hearing, which freezes the money, then a hearing at which a judge decides whether to make the order final. Under Part 72 of the Civil Procedure Rules a bank served with an interim order must search for all accounts held by the debtor and report within seven days whether each is in credit. The fee is £139.
Timing decides everything, and the guidance is unusually candid about it. The interim order freezes only the money in the account on the day it is served on the bank. If the account is overdrawn that day, nothing is caught; if it arrives the day before the debtor’s salary is paid in, you are likely to receive little or nothing. An order cannot be made against a joint account unless the debt is owed by all the account holders, and a debtor in hardship can apply for some of the frozen money to be released for ordinary living expenses. A well-timed order against an account you know is in funds can recover the whole debt in one step; a poorly timed one recovers nothing and still costs the fee.
Charging order: property
A charging order places a charge on the debtor’s property, such as a house or land, for the amount you are owed. The application is made on form N379 to the Civil National Business Centre, proceeds through an interim order that you must register with HM Land Registry, and becomes final unless objections succeed. Under the Charging Orders Act 1979 the court considers all the circumstances, including the debtor’s personal circumstances and prejudice to other creditors, and the fact that the debtor is paying by instalments without default does not prevent an order, though the court must take it into account. The fee is £139 for each separate charging order.
Understand what a charging order does not do. It does not put money in your account; it secures the debt, so that if the property is sold your charge is paid out of the proceeds after earlier charges such as a mortgage. For a debtor who owns property but has no ready money, that security can be valuable in itself.
Forcing an actual sale is a separate, harder step: the creditor must bring a fresh claim for an order for sale under rule 73.10C of the Civil Procedure Rules, and where the judgment enforces a regulated agreement under the Consumer Credit Act 1974, no order for sale can be made to recover an amount below £1,000. A charging order is best understood as the long game: pressure and security, not quick payment.
Choosing the route and the fees
The choice is not exclusive. The rules allow a judgment creditor to use any available method of enforcement, and to use more than one method at the same time or one after another, though each application carries its own fee and its own risk.
Warrant of control, fee £96. Fits a debtor with visible, saleable possessions.
Attachment of earnings, fee £139. Fits a debtor in steady employment; useless against the self-employed.
Third-party debt order, fee £139. Fits a debtor with a known account in funds; timing decides everything.
Charging order, fee £139. Fits a debtor who owns land or property; security now, payment on sale.
Two disciplines protect your money before you spend it. Match the method to a verified asset, not a hope: an order aimed at an asset the debtor does not have is a donation to the court fee account. And keep the court informed: if the debtor pays you during enforcement proceedings, you must tell the court immediately, particularly before any hearing. The fee figures here are those in the current civil court fees guidance, which is revised periodically, so check the fee before you file rather than relying on this piece months from now.
The closing point
Winning the case earns you the judgment; collecting the money is a second campaign with its own map. The creditors who recover are rarely the ones with the biggest judgments. They are the ones who found out what the debtor actually had before choosing where to aim.
Source anchors
HMCTS guidance on the four main enforcement routes, the £5,000 warrant limit and fee risk.
HMCTS guidance on applying for both orders, including timing, hardship and Land Registry registration.
The rules governing enforcement methods, orders to obtain information, third-party debt orders and charging orders.
The statutory taking-control-of-goods procedure that warrants and writs of control operate under.
The current HMCTS fees for warrants, attachment of earnings, third-party debt orders, charging orders and orders to obtain information.
The £1,000 minimum for orders for sale enforcing charging orders over regulated consumer credit debts.
These anchors support the enforcement framework described in this article; they are the official guidance, rules and legislation on which the procedural points rest.
Enforcement route decision point
Get a free written assessment of the enforcement route
Legal Lens can structure a preliminary written review of your judgment and what is known about the debtor, mapping the enforcement options against the assets they are most likely to reach.
Warrant, attachment of earnings, third-party debt order or charging order, matched to the debtor’s circumstances.
The fees each step carries, and the order in which the realistic options should be tried.
Assessment outputs
Enforcement options ranked against the debtor’s known assets.
The forms, fees and information each route requires.
Independent Legal Lens consultancy. Legal Lens is not a regulated solicitors’ firm. A preliminary assessment is not a substitute for regulated legal advice where that is needed.