 Written by
Housing – tenancy deposits – litigants in person
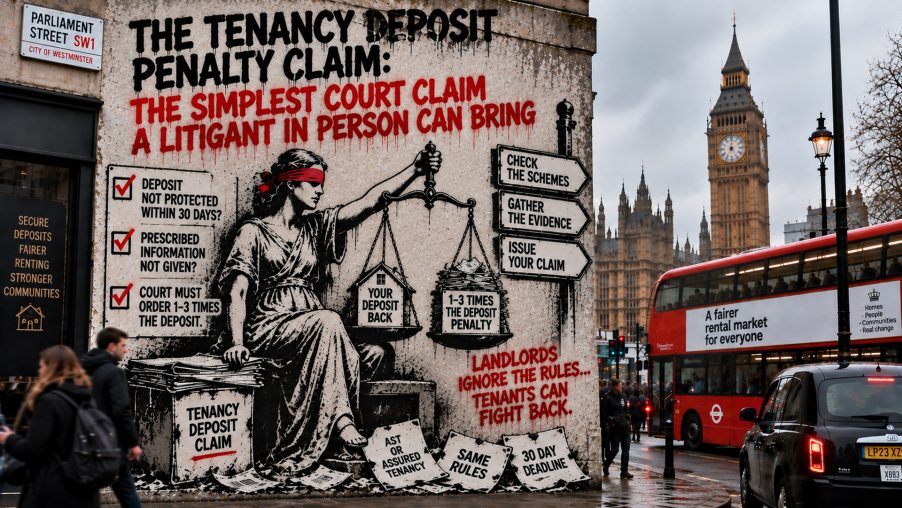
Most civil claims ask a court to put a value on a loss. The tenancy deposit penalty claim is different: the remedy is written into the statute. If a landlord failed to protect a deposit in an authorised scheme within 30 days, or failed to give the tenant the prescribed information about that protection, the court must order the deposit to be repaid or secured and must order a penalty of between one and three times the deposit. That makes it one of the most winnable first claims a litigant in person can bring – provided the evidence is gathered before issue.
Snapshot
The deposit penalty claim turns on documents, not impressions: what the scheme records show, what the landlord gave the tenant in writing, and when. Liability is close to mechanical once the breach is proved; the court’s remaining discretion is about the size of the penalty, not whether one is owed. The work that wins these claims is done before issue: checking all three schemes, preserving the results, and assembling a short, dated evidence bundle.
Why this claim is different
Most money claims require the claimant to prove both that the other side did something wrong and that the wrong caused a quantifiable loss. The deposit penalty claim removes the second half of that problem. A landlord who receives a tenancy deposit must comply with the initial requirements of an authorised tenancy deposit scheme within 30 days of receiving it, and must give the tenant – and anyone who paid the deposit on the tenant’s behalf – prescribed information about the scheme, again within 30 days. Those are hard duties with a fixed clock, and they apply despite any agreement to the contrary.
The remedy is just as hard-edged. Where the court is satisfied that either duty was breached, it must order the deposit repaid or paid into an authorised custodial scheme, and must order the landlord to pay the applicant between one and three times the amount of the deposit, each within 14 days of the order. There is no need to prove financial loss, distress or detriment. The penalty follows the breach.
One piece of housekeeping first. On 1 May 2026 assured periodic tenancies replaced assured shorthold tenancies, and deposits on the new assured tenancies must be protected in one of the same three schemes operating in England and Wales: the Deposit Protection Service, MyDeposits and the Tenancy Deposit Scheme. The Renters’ Rights Act 2025 amended the deposit provisions so that they now run with assured tenancies, with a transitional rule preserving the long-standing reach back to deposits paid on or after 6 April 2007 for tenancies that were shorthold immediately before the change. Whatever the tenancy is now called, the practical analysis below is the same.
The two duties landlords owe
The first duty is protection. The landlord must deal with the deposit in accordance with an authorised scheme and complete that scheme’s initial requirements – the steps the scheme itself imposes on receipt of a deposit – within the 30-day window. A landlord who pays the deposit into a custodial scheme on day 40 has still breached the duty, even though the money is safe.
The second duty is information, and it is the one landlords most often miss. The prescribed information is set out in a 2007 Order and is specific: the scheme administrator’s contact details; the scheme’s leaflet material explaining how the legislation works; the scheme’s procedures for repayment and for disputes, including resolution without litigation; the deposit amount and the property address; the parties’ details; the circumstances in which the landlord may retain the deposit; and a certificate signed by the landlord confirming the information is accurate. It must be given in the prescribed form or in a form substantially to the same effect.
Critically, the two duties are independent. The Court of Appeal has held that a landlord who protects the deposit but fails to give the prescribed information is still liable for the penalty: the obligation to provide the information is of equal importance to the duty to safeguard the deposit, and it is no answer that the tenant could have found the scheme’s procedures by making their own enquiries. That distinction matters in practice, because agents frequently protect the deposit and then serve nothing, or serve a generic leaflet that omits the tenancy-specific certificate the Order requires.
Check the scheme records first
The starting point is not the claim form but the schemes themselves. Each scheme administrator can confirm whether a deposit is being held in accordance with its scheme, and a tenant told that a particular scheme applies, but who cannot obtain that confirmation, has a freestanding ground for the claim. The claim is made by application to the county court, and it can be brought by the tenant, by anyone who paid the deposit on the tenant’s behalf, or – because the statute expressly covers tenancies that have ended – by a former tenant after the tenancy is over.
Ask each scheme to confirm the deposit, not just the one the landlord named.
Write to the landlord or agent asking which scheme applies and when the deposit was protected.
Keep dated screenshots, scheme confirmations and replies exactly as received.
Older tenancies need one extra check. Where a fixed-term shorthold tenancy rolled into a statutory periodic tenancy, the Court of Appeal treated the deposit as paid and received afresh for the new tenancy, so the protection and information duties arose again at that point. A landlord who protected the deposit for the original fixed term but did nothing when the tenancy changed shape may therefore be in breach even though the money never moved. With the move to periodic tenancies in May 2026 this trap will fade, but it remains live for the many deposits whose history crosses the changeover.
The evidence the claim needs
Because liability is document-driven, the bundle is short. It should contain: the tenancy agreement; proof that the deposit was paid, usually a bank statement or receipt; the scheme check results and any written confirmation from the scheme administrators; the prescribed information the landlord served, if any, or a clear statement that none was served; and the correspondence asking the landlord about protection. Each item should be dated, because the 30-day clock is the whole case.
Two habits repay the effort. First, test the prescribed information against the Order line by line rather than treating any leaflet as compliance: the missing item is usually the signed certificate or the tenancy-specific details, and the gap is easy to state precisely in the claim. Second, keep the evidence in the form it will be filed: a tidy, paginated bundle reads to the district judge as exactly what it is – a statutory breach with documents attached. Evidence turns confusion into an argument; here, it usually removes the argument altogether.
Issuing under Part 8
The claim is started in the county court using the Part 8 procedure, which exists for claims where the court’s decision is sought on a question unlikely to involve a substantial dispute of fact. The claim form must state that Part 8 applies, set out the remedy sought and the enactment relied on – section 214 of the Housing Act 2004 – and be verified by a statement of truth. The claimant’s written evidence is filed with the claim form and served with it; the defendant must file an acknowledgment of service within 14 days; there is no default judgment under Part 8; and the claim is treated as allocated to the multi-track.
That shape suits the claim: the court is asked to compare dates on documents against a statutory deadline, not to prefer one account of a dilapidations dispute over another. If the defendant does contend there is a substantial dispute of fact – that the money was returned, or was never a deposit at all – the rules let them say so in the acknowledgment of service, and the claim can be moved onto the ordinary track.
A court fee is payable on issue. The current figures are in the civil and family fees list, form EX50, and help with fees is available for people on certain benefits or a low income, so the fee position should be checked before issue rather than assumed. The order sought has two limbs: repayment or securing of the deposit, and the penalty payment.
What landlords can and cannot argue
Knowing the real battleground keeps the claim short. Some arguments are simply closed. Protecting the deposit late does not erase the breach: in a 2014 High Court appeal the landlords protected the deposit and served the information months late, admitted the breach, and the penalty remained mandatory – the only question was where in the one-to-three-times range it should land. And as already noted, a protected deposit is no answer to missing prescribed information, because the duties are independent.
“We protected it eventually.” Late compliance still breaches the 30-day duty, and the penalty follows the breach. “The tenant knew which scheme it was.” The statute requires the landlord to give the information; the tenant’s own research is no substitute.
The facts: the deposit was protected in time, or information substantially to the same effect was given. And the level: the court chooses the multiple, and culpability is the key factor.
On the level, the courts have treated culpability as the most relevant factor. In the same 2014 appeal, first-time landlords let down by their professional managing agents were held entitled to be placed at the lowest end of the scale – one times the deposit – and the High Court refused to disturb that assessment. A claimant should expect a portfolio landlord to be argued upwards and a genuine, quickly corrected slip to be argued downwards – and should address the point head-on rather than pretend the discretion does not exist.
The 2025 Act also replaced the old possession-notice sanction. A court may now make a possession order only if the deposit is held in accordance with an authorised scheme, the scheme’s initial requirements have been complied with, and the prescribed information has been given, subject to limited exceptions – among them that the deposit has been returned or that a penalty claim has already been determined, withdrawn or settled. For a tenant facing possession proceedings, the penalty claim and the possession sanction are two halves of the same scheme.
Source anchors
The framework described in this article rests on primary sources. They support the legal framework; they do not prove the facts of any individual tenancy, which is a matter for the reader’s own evidence.
Sections 212 to 215: the protection and prescribed-information duties, the county court claim and the one-to-three-times penalty.
Section 26 applies the deposit regime to assured tenancies and substitutes a new possession sanction in section 215.
Part 8: the alternative procedure for claims unlikely to involve a substantial dispute of fact.
Home of the judgments discussed here on late protection, prescribed information and replacement tenancies.
The closing point
The public lesson is simple. Parliament wrote the penalty into the statute, so the claim does not ask the tenant to prove a loss or to fight technical litigation over a few hundred pounds. The statute did the heavy lifting; the tenant’s job is the discipline of dates, screenshots and a short bundle. For a reader new to litigation, there is no kinder first claim – and no better place to learn that procedure, properly used, is the point rather than the obstacle.
Deposit claim decision point
Get a free written assessment of the deposit claim
Legal Lens can structure a preliminary written review of a tenancy deposit position: whether the statutory duties were met, what the scheme records show, and how a Part 8 claim would be put.
The protection and prescribed-information duties checked against the scheme records and the tenancy paperwork.
How the claim would be framed under Part 8, the evidence bundle it needs, and the realistic penalty range.
Assessment outputs
The duties, the dates, the documents and the live dispute.
Scheme records, correspondence and the gaps to close before issue.
Independent Legal Lens consultancy. Legal Lens is not a regulated solicitors’ firm. A preliminary assessment is not a substitute for regulated legal advice where that is needed.