 Written by
Debt claims – pre-action protocol – practical guidance
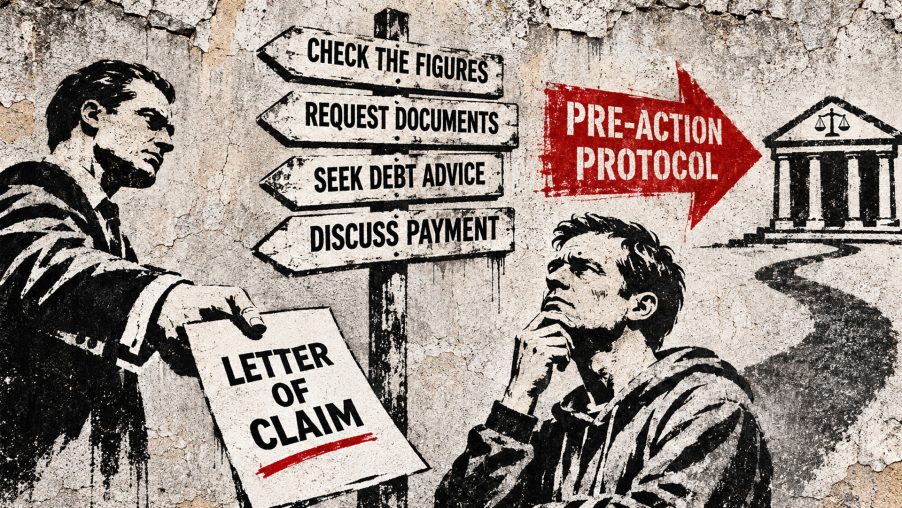
A letter threatening court proceedings is not yet a claim form. For many business-to-individual debt claims, it is the start of a structured pre-action process: a chance to check the figures, obtain documents, seek debt advice and discuss payment before litigation begins.
Snapshot
The Pre-Action Protocol for Debt Claims gives an individual debtor a practical opportunity to engage before a business issues proceedings. The first response period is normally 30 days from the date at the top of the letter of claim. A document request or a request for debt-advice time can then affect when proceedings should follow.
Asking for information is different from ticking the box that agrees the debt. Pre-action engagement is not a substitute for responding to court papers if a claim is issued. Keep the envelope, the letter, every enclosure and a copy of whatever you send back.
When the protocol applies
The Debt Claims Protocol applies where a business, including a sole trader or public body, claims payment of a debt from an individual, including an individual who is a sole trader. It does not generally cover a business-to-business debt unless the debtor is a sole trader. That scope determines whether the letter, forms and response periods described below apply.
Its aims are early engagement, a sufficient exchange of information to identify the dispute, resolution without proceedings where possible, reasonable and proportionate conduct, and efficient management of any case that must go to court. A repayment plan and alternative dispute resolution are part of that exercise, not signs that the creditor has already proved the debt.
For the debtor, the useful starting question is therefore not simply “Do I agree with this demand?” It is “What exactly is being claimed, on what basis, and what information do I need before I can answer?” The protocol supplies a structure for asking those questions.
What the letter of claim should contain
The process begins with the creditor’s letter of claim. It should state the amount and whether interest or other charges are continuing; explain the agreement relied upon; give assignment details where the debt has been sold or transferred; explain why proceedings are contemplated despite current instalments, if that is happening; and provide payment details, contact arrangements for discussing options and the address for the reply form. For an oral agreement, the expected detail includes who made it, what was agreed and when and where. For a written agreement, the letter should identify its date and parties and explain that a copy can be requested.
The creditor should also provide an up-to-date account position, covering interest and administrative or other charges, together with the protocol’s Information Sheet and Reply Form and a Financial Statement form. The letter should be clearly dated near the top of its first page and posted on that date or, if that is not reasonably possible, the following working day. These are working documents: the reply form lets you identify your position, while the financial statement helps frame an affordable payment proposal.
Check the delivery channels as well as the content. The letter should be sent by post. Since 1 October 2026, a creditor with a personal email address for the debtor should also send it to that address; if there is no personal email address but other personal electronic contact details are known, the creditor should use at least one of those methods. An explicit request by the debtor not to receive correspondence by post, accompanied by alternative details, changes that starting point.
Build the record from day one. Check the debt against your own statements and receipts. List anything missing, preserve the complete pack and note when each communication arrives. Do not discard a partially completed reply: it may still be useful evidence of engagement.
The reply and the 30-day periods
The initial period is 30 days from the date at the top of the letter, not 30 days from the day you happen to read it. If the debtor does not reply within that period, the creditor may start proceedings, subject to its remaining obligations and to allowing for the possibility that a reply was posted near the end of the period. That does not turn the letter itself into a court judgment. Prompt engagement is therefore sensible.
The debtor should use the Reply Form, request any documents needed and enclose relevant material, such as evidence of payments omitted from the creditor’s figures. A partially completed form should be treated by the creditor as an attempt to engage, prompting contact to discuss it and obtain the further information needed. The prescribed form allows you to agree the debt, agree only part, say that you do not know whether you owe it, or dispute it. It also provides routes for proposing payment and requesting information.
A useful reply identifies the position precisely. If the dispute concerns the balance rather than the whole debt, give the figure you accept and explain the difference. If a payment is missing, identify its date and attach proof. If you cannot yet take a position because the agreement or account history is missing, say what you need rather than guessing.
Returning the form does not mean the creditor can issue immediately on day 31 regardless of what follows. The further periods connected with debt advice and requested documents are considered below, and the protocol also expects a final notice before issue where there has been engagement without agreement.
Debt advice, documents and affordable payment
The protocol recognises that a debtor may need help both to understand liability and to assess affordability. If the debtor indicates that debt advice is being sought, the creditor must allow a reasonable period for it to be obtained. Proceedings should not start less than 30 days from receipt of the completed Reply Form or less than 30 days after the creditor supplies requested documents, whichever is later. If advice cannot be obtained within 30 days of the reply, the debtor must provide the details requested in the form, and the creditor should allow reasonable extra time where reasonable.
Use Section 3 of the Reply Form to identify the adviser, the advice being sought and any appointment. If delay is unavoidable, explain why and when advice is expected. This is more useful than simply writing “I am seeking advice” without the supporting detail. Keep the appointment confirmation and update the creditor if circumstances change.
Document requests should be equally concrete. When the debtor requests a document or information, the creditor must either provide it or explain why it is unavailable within 30 days of receiving the request. The Reply Form suggests possibilities including the written contract, a full statement explaining interest, charges and payments, an interest calculation and a notice of assignment. Ask for what bears on your position; there is little value in turning the exercise into an unfocused demand for every document the creditor holds.
Where the debtor indicates that time to pay is needed, both parties should try to agree instalments based on income and expenditure. The creditor should have regard, where appropriate, to the Standard Financial Statement or equivalent guidance and should give reasons if it rejects the proposal. An offer should be sustainable rather than merely large enough to produce short-term silence. Provide a realistic financial statement and supporting figures, and keep a record of the proposal and any response.
Why engagement matters, including for costs
Pre-action engagement is intended to resolve the dispute or at least narrow it. If disagreement remains, the parties should consider appropriate alternative dispute resolution, which may include negotiation, a relevant ombudsman route or mediation. They should review their positions and try to avoid proceedings or narrow the issues. For a debtor, a focused reply can make the real dispute visible: liability, the arithmetic, enforceability, affordability, or a combination of those issues.
Where the debtor has responded but no agreement has been reached, the creditor should give at least 14 days’ notice of its intention to start proceedings, unless exceptional circumstances require urgent action. That is separate from the initial 30-day response period and from the further 30-day periods following a reply or documents.
There is also a costs reason to engage. If litigation follows, the court expects compliance with a relevant protocol. It can take non-compliance into account when managing the case and making costs orders, and may impose sanctions; it looks at compliance in substance rather than concentrating on every minor or technical infringement. Silence therefore discards an opportunity to show a reasonable approach and to clarify what is genuinely disputed.
Under CPR 44.2, the court has discretion over whether costs are payable, their amount and when they must be paid. Although the general rule is that an unsuccessful party pays the successful party’s costs, the court may make a different order after considering all the circumstances, including pre-proceedings conduct, compliance with the relevant protocol, the reasonableness of pursuing or contesting an issue and engagement with alternative dispute resolution. Engagement does not guarantee a favourable costs outcome, and the applicable costs rules still depend on the proceedings. It does, however, create a clearer record from which reasonableness can be assessed.
If proceedings follow
One boundary needs to remain clear. Pre-action protocols do not alter statutory limitation periods for starting proceedings. If proceedings have to be issued to comply with a limitation deadline before the protocol process is complete, the parties should apply for a stay while they comply. Correspondence should not be used as a reason to overlook a limitation issue.
The other boundary is procedural. Once proceedings exist, CPR 15.4 generally requires a defence within 14 days after service of the particulars of claim, or within 28 days after that service if the defendant files an acknowledgment of service under Part 10. A defendant who wishes to defend all or part of a claim must file a defence, and failure to do so can allow the claimant to obtain default judgment where Part 12 permits. The earlier reply form is therefore not a defence filed with the court.
Read any claim pack as a new procedural event, with its own dates and requirements. The work done before issue should still help: the chronology, document requests, evidence and identified issues can inform the next response. What it cannot safely do is replace that response.
Source anchors
These official sources set out the procedural framework discussed above.
The prescribed letter, response, document, advice, repayment and pre-issue steps.
The amendment to paragraph 3.3 on postal and electronic delivery, effective 1 October 2026.
The compliance, sanctions, settlement and limitation framework.
Rule 44.2 on discretion, conduct before proceedings and protocol compliance.
The separate rules on filing a defence after proceedings have begun.
The practical point
The protocol gives the debtor more than a waiting period. Used properly, it creates an organised exchange about liability, evidence and affordability before either side commits further to litigation. A careful reply cannot guarantee settlement, but silence leaves the creditor’s account unexamined and gives you no better position from which to respond if court papers arrive.
Debt-response decision point
Get a free written assessment of your pre-action response
Legal Lens can structure a preliminary written review of the letter pack, the issues you identify and the documents needed for a clear response.
Separate what is accepted, disputed, unknown and dependent on further documents.
Organise the reply, advice details, payment proposal and supporting evidence.
Assessment outputs
Liability, amount, documents and payment questions.
The records needed to support a coherent response.
Independent Legal Lens consultancy. Legal Lens is not a regulated solicitors’ firm. A preliminary assessment is not a substitute for regulated legal advice where that is needed.